













AASAAN BUYER’S FIELD GUIDE · INDIA
Know what each site owes, what needs approval and what needs cash.
Construction accounting software connects project transactions with financial records. Indian builders and contractors should evaluate supplier bills, subcontractor certification, advances, retention, payments, collections and accounting integration together. This guide explains the workflows, demonstrates settlement and cash planning, and provides practical checks for choosing software that fits your site-to-accounts process reliably.
Your accountant says the supplier balance is ₹4.6 lakh. The site says some material is still under review. The payment list says ₹2 lakh. Before the owner releases money, someone has to explain all three numbers.
That explanation is the real buying test for construction accounting software in India. This guide follows the records behind the numbers, then gives you worked examples and questions to use in a live demonstration. The amounts and scenarios are illustrations, not customer results.
Which construction accounting software should you choose?
Choose software by tracing a bill, not by counting dashboard tiles. If your main problem is maintaining the books, start with accounting depth: ledgers, reporting, reconciliation, permissions and the statutory work your accountant actually performs. If the problem begins before the bill reaches accounts, you also need construction controls: purchase references, receipts, measured work, authorisations and project allocation.
A contractor with reliable books but late site records may need a construction platform connected to its existing accounting system. A developer collecting instalments from buyers needs a separate review of customer records, unit references, demand schedules and receivables. A business with several companies must test which legal entity owns each transaction before looking at a consolidated dashboard.
For teams evaluating site-to-accounts control, Aasaan deserves a place on the shortlist. Its published offering includes supplier and client billing, party ledgers, payments, work orders, RA billing and Tally integration. The right next step is a demonstration using your documents, including a partial receipt or disputed quantity. Use the checklist in this guide to compare the outcome against your actual requirements.
What is construction accounting software?
Construction accounting software records and organises financial transactions for businesses delivering projects. A useful setup connects the company, project, party, work package and source document so the accounts team can explain an amount rather than merely display it. Depending on the product and configuration, this may involve the accounting application itself, a construction ERP, or connected systems with clearly assigned responsibilities.
The important distinction is between recording a transaction and establishing why it should be recorded. A supplier invoice establishes a claim. A receipt confirms what arrived. An inspection may establish what was accepted. A payment instruction authorises settlement. A bank record establishes what moved. These are related events with different dates and owners.
Here is the test: choose one outstanding supplier amount. Can someone show the invoice, accepted receipt, project allocation, credit note if any, previous payment and remaining balance? If that takes several phone calls, the weak point is the chain between records. New software is useful only when it makes that chain easier to maintain and review.
When has your construction business outgrown its current setup?
An owner asking for a report is normal. An owner needing to reconstruct every report is a warning sign. Look for recurring exceptions: bills waiting because the site has not confirmed receipt, the same vendor recorded under different names, advances carried indefinitely, and payment lists that disagree with party statements.
Another signal is a report whose meaning changes depending on who prepared it. The project manager calls an amount an expense because work was completed. The accounts team calls it unpaid because the invoice has not been posted. Treasury calls it committed because payment is planned next week. All three statements may describe different stages of the same obligation.
Before replacing anything, list the last ten delays or disputes and identify where each began. If most began with missing measurements, a ledger replacement alone will not solve them. If site evidence is already complete but month-end books still need extensive manual reconciliation, investigate accounting configuration, processing capacity and integration. Software selection should address the observed bottleneck.
Builders, contractors and developers need different accounting workflows
A main contractor typically needs to connect client contracts and certified work with subcontractor bills, purchases, labour and collections. A property developer may additionally manage unit-linked customer accounts, collection schedules and project-level funding decisions. An interior contractor can have many smaller jobs, frequent variations and supplier advances, making document volume and allocation particularly important.
Do not infer the required accounting treatment from the business label alone. The contract, legal entity, applicable accounting framework and nature of the transaction matter. Project reporting can sit alongside statutory accounts, but the two must reconcile through an agreed policy.
Invite the people who will use the software to the evaluation. The owner should ask about visibility and funding. The accountant should ask about postings, corrections and reconciliation. The quantity surveyor should ask about certification and cumulative measurements. The site storekeeper should test partial receipts and returns. A demo that convinces only the owner can still fail during the first payment cycle.
Cost tracking, accounting, cash flow and profit: what is the difference?
Cost tracking asks what resources a project has consumed or is expected to consume. Accounting records transactions under the business’s adopted policies and reporting framework. Cash flow follows the timing of money received and paid. Profit follows recognised income and expenses; it is not simply the difference between the project’s bank receipts and payments.
An equipment advance can reduce available cash before the related cost is recognised. A bill can be approved and unpaid. Material can be received but remain unused. Client money can arrive before it is recognised as revenue. A retention balance can remain outstanding even when the main bill is settled. Keep those differences visible instead of labelling every amount ‘expense’.
Consider an illustrative project with ₹30 lakh collected and ₹24 lakh paid. The ₹6 lakh cash difference is not automatically profit. The project may still owe suppliers and subcontractors, hold advances, or have work whose revenue and costs require review. Ask the accountant for the reporting basis before using a project margin to make a distribution or funding decision.
| Record | What it answers | What it does not prove |
|---|---|---|
| Cost incurred | What has been recognised as cost under the reporting basis? | That cash has been paid. |
| Outstanding liability | What remains owed on a reconciled basis? | That it is all approved and due today. |
| Payment proposal | What is proposed for this run? | That the bank has settled it. |
| Bank receipt | What money arrived? | That it is recognised revenue. |
| Project profit | What is the result under the adopted policy? | That the project has enough cash next Tuesday. |
Set up the master records before the first transaction
Use consistent company, project, party and work-package references. Identify which fields are mandatory for each transaction. A site should not have to choose from three similar vendor names, and an accountant should not have to guess which project ‘Building work’ refers to. Establish who may create or amend a master record and who reviews the change.
Keep a project code stable even if the public project name changes. Where one supplier serves several sites, maintain the agreed party identity and allocate transactions to the correct project and company rather than creating duplicates to make a report easier. Validate registration and bank information through the business’s verification process before using it.
Agree document numbering and duplicate checks before migration. Use the supplier identity, document number and financial period as review fields, while allowing legitimate exceptions to be investigated. Credit notes, revised invoices and different document series need careful handling. A duplicate alert is a prompt to review evidence, not proof that the supplier has done something wrong.
Follow one supplier bill from the site to the ledger
Suppose Site A orders 100 boxes of tiles. Sixty arrive, four are held for review and 56 are accepted. The supplier sends an invoice for all 100. Before accounts schedules payment, the team needs to explain the difference between ordered, delivered, accepted and invoiced quantities.
The storekeeper records the actual receipt. The responsible reviewer resolves the four held boxes. Purchasing confirms the remaining delivery and invoice arrangement. Accounts checks the approved order, received quantities and the supplier’s claim, then records or holds the transaction according to policy. A partial delivery does not automatically tell you the correct payment: contractual terms may allow an advance or another agreed arrangement.
Retain the exception and its resolution. If the supplier later replaces the four boxes or issues a credit note, link that event to the original record. When a payment is made, update the settlement reference and reconcile it to the party balance. The objective is that the next person can follow the transaction without asking the storekeeper to remember last month’s delivery.
| Step | Record to inspect | Review owner |
|---|---|---|
| 1. Order | Approved scope, quantity, rate and terms | Purchasing or commercial team |
| 2. Receive or measure | Actual receipt, acceptance or certified work | Site/storekeeper or QS |
| 3. Review the claim | Invoice, bill, credit and exception | Accounts with source-record owner |
| 4. Authorise settlement | Approved payable and beneficiary review | Authorised approver |
| 5. Settle and reconcile | Bank reference, party allocation and balance | Accounts/treasury |
What should the accounts team see before accepting a site invoice?
A useful invoice pack answers five questions without making the accountant search different chats: which business owes the amount, which project received the supply, what was agreed, what was accepted and what adjustment remains open. The pack can consist of linked records rather than one large PDF. What matters is that the references remain usable after the person who uploaded them moves to another site.
For a material purchase, retain the approved order or other purchase authority, delivery and receipt references, applicable acceptance record and supplier invoice. For a service, use the agreed service confirmation or measurement evidence. A small recurring service may follow a simpler approval route than a major subcontract, but that route should still be defined.
Distinguish a missing document from a commercial disagreement. If the invoice is correct but the receipt has not been uploaded, obtain the evidence. If the site disputes the quantity, resolve the quantity. If the supplier has invoiced before an agreed milestone, check the contract. A single pending label makes these three cases look identical and sends follow-up messages to the wrong person.
The approval record should identify the reviewer, decision and date, with any conditions attached. Accounts can then determine how to process the transaction under the business’s policy. Payment release remains a separate decision; a complete document pack does not mean every amount is immediately due.
How should purchase orders, GRNs and invoices be matched?
A goods receipt note, or GRN, records receipt information; an invoice records the supplier’s financial claim. Matching should examine quantities, units, rates, accepted extras, freight and other applicable charges. A material described in bags on the order and tonnes on the invoice needs a documented conversion, not a convenient manual adjustment.
Set a route for differences. A quantity mismatch belongs with the receiving or purchasing team. A disputed rate goes back to the approved order or instruction. Missing documentation needs an owner and deadline. Approved exceptions should carry a reason and authorisation so they do not reappear at every review.
Test both normal and awkward cases in software: two receipts against one order, one invoice covering several receipts, a short delivery, a return and a credit note received after payment. Ask whether the application displays the remaining order quantity and the unresolved invoice difference. A screen showing ‘matched’ is useful only if the team can explain what was compared.
Materials purchased, stored, consumed and transferred need different records
Imagine Site A receives 100 bags of a material, issues 60 to a workfront and transfers 20 to Site B. The physical movement is not explained by showing the purchase bill alone. Record receipt, issue, transfer and remaining stock separately, including any accepted loss or adjustment. The accountant then applies the appropriate accounting policy to those operational records.
Keep the issuing and receiving ends of an inter-site transfer connected. The receiving project should confirm quantity and reference the same transfer. Otherwise, a storekeeper may remove stock from Site A while Site B waits for a receipt that nobody recorded. Management can end up seeing stock missing from both sites or counted twice.
Test the reporting effect before launch. Can the project manager see where the stock is? Can accounts identify which project has been charged under the agreed rules? Does a return refer to the original issue? Who reviews a physical count difference? A stock balance and an accounting cost report answer different questions and should be bridged explicitly.
Do not assume a stock transfer is a new external sale, a new cash payment or an identical accounting event in every situation. The entity structure and transaction matter. Keep the operational evidence accurate and have the finance team determine the required entries. This prevents the inventory workflow from quietly imposing an accounting treatment.
How should subcontractor RA bills be reviewed?
A running account bill is usually a periodic claim under a work contract. For review purposes, distinguish the contractor’s claimed quantity, the quantity verified by the site or quantity surveyor, and the quantity certified under the approval process. Keep the current-period movement separate from cumulative totals to avoid paying again for work certified earlier.
Start with the work order, approved rates and measurement reference. Review additions, omissions and variations against their authorisation. Keep retention, advance recovery, withholding and previous settlement visible as separate components. The contract and the finance team’s treatment determine how those amounts are applied.
For example, a subcontractor’s cumulative claim includes ₹12 lakh of work, while the last certified cumulative value was ₹8 lakh. The change is ₹4 lakh before adjustments; it is not a new ₹12 lakh entitlement. The accountant should be able to trace the certified movement and deductions back to the source records. A plain net amount on a payment list cannot provide that explanation.
Connect labour attendance, wage preparation and labour cost review
Separate direct employees, daily-paid workers and subcontractor labour in the records. The attendance register can show site presence or deployment; it does not automatically establish that every hour is payable or that work under a measured subcontract has been accepted. Define which records support the relevant wage or contractor process.
For direct labour, the responsible team reviews attendance exceptions, approved overtime and applicable wage inputs before preparing payment. Accounts then reconciles the approved payout with the payment record. A cash advance issued earlier should have a visible balance and authorised adjustment rather than being deducted from memory during payday.
For a measured-work subcontract, verify quantities and rates against the work order even when the labour attendance is available. A crew’s presence can help investigate a delay, but payment may be based on certified output. Charging the same workforce through both direct wages and a subcontract bill is a scenario worth testing if your business uses mixed arrangements.
At the reporting cut-off, ask whether the period’s work has been captured and whether the corresponding wage or contractor obligation has been reviewed. Keep unprocessed items visible for the accountant to assess. The aim is to explain why labour cash paid, payroll prepared and project labour cost may differ at a particular date.
Keep advances, retention and credits separate
An advance, retention and credit note can all reduce a payment instruction, but they represent different things. An advance records money already provided against an agreed arrangement. Retention is an amount withheld under contract, with release conditions. A credit note adjusts a supplier’s claim. Mixing them into ‘deductions’ hides what remains to be reconciled.
Maintain a schedule for each balance. An advance schedule should show opening amount, additions, agreed recoveries and closing balance. A retention schedule should include the linked contract and release conditions. A credit register should show whether the credit was received, recorded, allocated and reflected in settlement.
Suppose an old advance is carried forward but the team cannot identify the recovery agreement. Investigate the contract and past payments before reducing a new bill. Similarly, do not release retention simply because a project is marked complete in an operational dashboard. Obtain the required approval and supporting evidence. The review should preserve both the current amount payable and the remaining contractual balances.
Review hired equipment and owned machinery on the correct basis
A machine can create several records: hire terms, allocation, usage, fuel, maintenance, operator charges and settlement. Agree which costs are included in the hire rate before comparing a supplier’s claim with the project log. A daily hire rate that includes an operator is not directly comparable with one that excludes the operator.
Suppose a hire invoice covers ten days while the site log shows six working days and four idle days. That does not automatically justify paying for six days. Check the contract’s treatment of standby, minimum hire, breakdowns, mobilisation and off-hire. Record the commercial decision and supporting logs before accounts processes the claim.
For company-owned machinery, agree the management-reporting treatment with finance. An internal equipment charge may help compare project performance, but it should not be mixed with an external cash payment or counted again in a consolidated report. Keep fuel and maintenance allocations traceable to the source records.
Ask the vendor to demonstrate a machine moving between projects during a reporting period. The team should be able to follow allocation dates, the approved charging approach and any shared charges. This is a more useful test than checking whether the product has an equipment icon on its dashboard.
Worked example: certified work is not the same as money due now
Assume an approved current claim has a certified value of ₹10 lakh before tax. The finance team has separately determined an applicable tax amount of ₹1.8 lakh. For this illustrative settlement, authorised retention is ₹0.5 lakh, advance recovery is ₹1 lakh, withholding is ₹0.2 lakh, credit adjustments are ₹0.1 lakh and previous payments allocated to this same claim are ₹3 lakh.
The remaining settlement amount is ₹10 + ₹1.8 − ₹0.5 − ₹1 − ₹0.2 − ₹0.1 − ₹3 = ₹7 lakh. These figures demonstrate the arithmetic, not the correct tax rate, deduction base or accounting entry for your contract. Use separately approved amounts and do not apply a retention percentage to a tax-inclusive value just because a calculator accepts it.
Check the scope of previous payments carefully. If the ₹3 lakh belongs to an earlier bill already excluded from the current claim, deducting it here would understate the balance. If the current value is cumulative, first reconcile the cumulative certification and settlements. The settlement calculator below uses a single defined claim or reconciled payable balance, with no overlapping inputs.
Track client billing, certification and collections independently
A contractor may submit a claim that the client has not certified. The client may certify a different amount, pay part of it and retain another component. Track these stages separately: submitted, under review, certified, invoiced where applicable, due and received. Include disputed amounts in an exception report rather than silently counting them as expected cash.
For developers, review customer and unit references, demand schedules, receipts, adjustments and overdue balances as a distinct workflow. An enquiry or booking entry should not be treated as evidence of an actual bank receipt. When a collection is received, allocate it against the correct customer obligation and legal entity.
Agree collection assumptions with the people responsible for follow-up. An owner may expect ₹20 lakh this month; accounts may have only ₹8 lakh with an agreed date. Show both as scenarios. A cash plan built on every outstanding amount being collected on time is a best-case assumption, not a reliable payment schedule.
Build an actionable receivables review instead of one overdue total
Group outstanding amounts by what needs to happen next. A claim awaiting certification needs commercial follow-up. A certified invoice with a near-term due date needs collection planning. A disputed amount needs a documented resolution. An unallocated receipt needs reconciliation. The same ageing number can hide all four situations.
For each important balance, record the responsible person, next action, expected date and basis for the collection assumption. Separate an agreed remittance date from an optimistic forecast. If a customer promises payment after a particular document is supplied, track that document as the immediate action.
Consider two balances of ₹5 lakh each. One has an agreed payment date next week. The other is disputed and has no resolution date. Showing ₹10 lakh as next week’s expected collection overstates the dependable input to the cash plan. Present confirmed and uncertain receipts separately, then review the funding effect of the uncertain amount slipping.
For property developers, maintain customer and unit references throughout the collection workflow and reconcile changes, adjustments and receipts against the applicable obligations. The system should make a partial receipt and its allocation understandable to both the customer-facing team and accounts.
Worked example: why the supplier ledger and payment list differ
Take an illustrative supplier with a reconciled opening liability of ₹4 lakh. Approved new bills add ₹6 lakh. A recorded credit reduces the claim by ₹0.4 lakh and allocated payments reduce it by ₹5 lakh. On this simplified common basis, the closing liability is ₹4.6 lakh. This is not automatically the amount to pay today.
Suppose ₹1.5 lakh is not yet due, ₹0.6 lakh has an unresolved supporting-record query and ₹0.5 lakh is retained under contract. The remaining ₹2 lakh may be considered for the payment run, subject to normal approvals and the agreed accounting treatment. The ledger total and payment proposal differ for explainable reasons. These amounts are mutually exclusive; do not subtract a credit or payment already included in an opening balance.
Build a bridge showing opening balance, new entries, credits, payments and closing balance. Then explain how the closing balance becomes the proposed payment. Keep invoices awaiting posting in a separate queue so management can see obligations that have not yet reached the ledger. This bridge is often more useful than a second dashboard displaying another unexplained number.
Reconcile payments to the bank, not just to a paid status
Payment preparation, bank submission and bank settlement are different events. Record enough information to trace the approved proposal to the actual movement. If a bank instruction fails or is returned, the supplier balance and payment status must follow the agreed correction process rather than remaining marked paid.
One bank transfer may settle several invoices. Several transfers may settle one bill. Retain the allocations so the bank amount can be reconciled with the party ledger and individual claims. If a supplier receives ₹5 lakh against three invoices, a payment reference on only one invoice leaves the other two looking unpaid.
Investigate unallocated bank items and receipts instead of placing them permanently in a generic project bucket. Obtain the source, purpose, entity and party reference. Record unresolved items with an owner and follow-up date so the close report does not imply that every movement has been explained.
Test a partial settlement followed by a failed second payment. Ask how the software displays the remaining balance, who can reverse or correct the failed item and what history remains. The final check is that the authorised payment, bank evidence and reconciled party balance agree, including any fees or adjustments handled separately.
An exception register that keeps bills moving
Use one queue with specific reasons instead of one generic pending status. Receipt confirmation pending, rate disagreement, missing measurement, duplicate review, tax review, approval pending and transfer failure need different owners. Give each item an amount, age, source reference, next action and due date. Escalation should follow the business priority and deadline.
For example, a ₹2 lakh material invoice is waiting for quantity confirmation. The storekeeper owns the accepted quantity, purchasing owns the supplier discussion and accounts owns the posting decision once evidence is complete. Asking accounts to clear the bill does not resolve the missing site record. Direct the question to the person who can answer it.
Separate commercial holds from funding constraints. If a bill is approved but the business has not arranged cash, record that explicitly in the payment planning process. Do not leave it in verification pending to make the approval report look cleaner. A transparent reason protects the usefulness of every report built from that status.
| Exception | Next useful action | Evidence needed to close |
|---|---|---|
| Quantity does not match | Ask receiving team to explain accepted quantity | Reconciled receipt or approved resolution |
| Rate disputed | Check order and approved changes | Authorised rate or credit |
| Advance unclear | Reconcile opening advance and recovery terms | Signed balance schedule and approved recovery |
| Transfer failed | Resolve mapping or validation error | One posted record and reconciliation |
| Approved but unfunded | Update funding plan and payment timing | Authorised payment schedule |
Who owns the answer when records disagree?
Assign a source-record owner and a resolution owner to important exceptions. The storekeeper can confirm what arrived, while purchasing may need to resolve the supplier claim. The quantity surveyor can explain certified work, while accounts reconciles certification against previous payments. Treasury can confirm a bank movement, while accounts allocates it to the correct balance. The owner or authorised manager decides the payment priority within the approval framework.
Write the decision into the shared record. If the purchasing lead resolves a quantity dispute on a call but the invoice remains on hold in accounts, the problem continues operationally. A useful closure identifies the agreed quantity or adjustment, who authorised it and which downstream record must now change. During the demo, ask the vendor to show that final handoff.
How should costs shared across projects be allocated?
Choose an allocation basis that reflects the cost and can be supported. Shared head-office costs, transport, staff time and machinery do not necessarily need the same driver. Document the purpose, basis, period and approval of each allocation rather than choosing the project that currently has the largest available budget.
For an illustrative shared transport charge of ₹1 lakh, management agrees to allocate by verified trips for the period: six trips to Site A and four to Site B. On that basis, the allocation is ₹0.6 lakh and ₹0.4 lakh. If the trip records are incomplete, the apparent precision of the calculation does not make the allocation reliable.
Keep the original transaction identifiable after allocation. The company-wide amount should reconcile to the source charge while project reports show the approved split. Reallocating the cost should leave an explanation of what changed and why, rather than silently overwriting a previous period’s report.
Before comparing site margins, ask whether the same allocation policy is applied consistently. One site can look more profitable simply because shared costs were assigned elsewhere. Have finance decide the accounting treatment and clearly label management allocations where they serve a different reporting purpose.
Worked example: a project can show progress and still need funding
Site A begins the week with ₹8 lakh available. Confirmed collections are ₹6 lakh and no additional funding is arranged. Planned payments are ₹3 lakh payroll, ₹8 lakh suppliers, ₹4 lakh subcontractors and ₹1 lakh other outflows. The projected closing cash is ₹8 + ₹6 − ₹3 − ₹8 − ₹4 − ₹1 = minus ₹2 lakh.
If management wants a ₹1 lakh closing buffer, the planning gap is ₹3 lakh. This does not mean the project lost ₹3 lakh. It means the selected week’s expected receipts and payments leave a gap against the chosen buffer. Changing the timing of a payment may change the weekly gap without changing the project’s ultimate profitability.
Review the dates behind the totals. A collection on Friday cannot fund a payment that must clear on Tuesday unless another source is available. Use the calculator as a period-level starting point, then review the daily sequence for material amounts. Do not include the same supplier amount in both ‘suppliers’ and ‘other outflows’.
Can you keep Tally and add construction ERP?
Yes, an integrated approach can be appropriate when the business wants to keep its established accounting application while improving site inputs and approval records. The key question is which system owns each record and which event makes it eligible to transfer. ‘Two-way integration’ is a description to test, not a complete implementation specification.
Define the company and ledger mappings, project references, document types, approval status and correction process. Ask what happens when the same supplier already exists in both systems, a bill is rejected during transfer, or someone edits a transaction after posting. Request a visible failure queue and reconciliation procedure rather than assuming every transfer succeeds.
Aasaan publicly lists Tally integration. During your demo, verify the supported versions, document types, direction of movement, timing, configuration and any connector charges for your proposed setup. Use a sample bill, correction and credit note. The most useful test ends with the site record, accounting voucher and party balance agreeing.
Accounting software, construction ERP or invoice automation?
These categories solve different parts of the problem. An accounting application can serve the statutory books and financial records. Construction ERP can coordinate commercial and operational transactions across projects. An invoice-automation tool can help capture and process documents inside an existing workflow. A business can use more than one category if ownership and reconciliation are clear.
Choose the smallest architecture that covers the required end-to-end process. Adding a site app, an approval app, a bill-capture tool and an accounting package can work, but each handoff needs monitoring. Conversely, buying an ERP with broad modules does not automatically provide the accounting depth your finance team requires.
When comparing products, separate demonstrated functions from configuration, integrations and future commitments. Record ‘shown using our sample’, ‘configuration required’, ‘separate product’ and ‘not available’ rather than assigning unsupported scores. Ask for the agreed scope in the proposal. A vendor should be able to explain where your operational records stop and statutory accounting begins.
| Architecture | Useful when | Demand proof of |
|---|---|---|
| Accounting application | Books and financial reporting are the principal need | Reconciliation, controls and finance-team requirements |
| Construction ERP plus accounting | Site evidence and commercial handoffs are the weak point | One complete transaction and a correction across systems |
| Invoice automation plus existing tools | Document capture is the specific bottleneck | Review, mapping, duplicate handling and exception route |
What should Indian teams verify about GST, TDS and revenue?
Verify the exact transaction and reporting workflow with your finance team. Tax treatment can depend on the supply, contract, entity, dates and applicable rules. A general buying guide should not promise that one rate or one withholding rule covers every construction business. Ask software vendors to show how approved tax settings are maintained, reviewed and corrected.
The GST portal describes GSTR-2B as an auto-drafted input-tax-credit statement. Use the official GSTR-2B guidance and current Invoice Management System advisories when designing the reconciliation process. Matching a supplier record is not, by itself, a complete assessment of whether credit can be taken. Keep the business’s eligibility review with the supporting records.
Revenue recognition also needs an agreed accounting basis. ICAI’s clarification on Ind AS 115 in the real estate context calls for evaluation of contract rights and obligations when considering recognition as construction progresses. A progress percentage, client bill or bank receipt should not be presented as an automatic revenue-recognition rule. Have your accountant approve how management reports bridge to the books.
Primary references: GST portal: GSTR-2B FAQs, GSTN: Invoice Management System advisory, and ICAI: clarification on Ind AS 115 in real estate. Confirm current transaction-specific treatment with your accountant.
Seven integration failures worth testing before purchase
Ask for a controlled test of a missing ledger mapping, an unavailable connector, an already transferred invoice and a correction to a posted bill. Then add a credit note, an amended project allocation and a transaction assigned to the wrong company. These are test scenarios, not allegations that a particular product has these faults.
For every scenario, record what the user sees, who is notified, where the item waits and how it is resolved. Confirm how the system prevents a retry from creating a duplicate. Ask whether cancellation or reversal in one application needs a corresponding action in the other. A technical success message is not enough unless the records and balances reconcile.
Agree a handover pack for the integration: supported transactions, master mappings, credentials ownership, operating instructions, reconciliation checks and support contacts. Include who monitors failures after launch. A connector can be functioning while a specific document remains unmapped, so daily responsibility must extend beyond checking whether the service is running.
What permissions and audit controls should you test?
List sensitive actions before assigning roles: creating a party, changing bank details, certifying quantities, approving a bill, preparing payment, releasing payment and changing a posted transaction. Decide which actions require another person’s review. The exact arrangement will depend on your team size, but responsibility should be explicit.
Test permissions with actual user accounts in the demonstration. Can a site user see unrelated projects or confidential balances? Can an approver change the underlying quantity without a record? Can the payment preparer also change the beneficiary? Ask what the audit log captures, how corrections are retained and who can export the records.
Use a controlled bank-detail-change example. Have one user request the change, another review it and the accounts team inspect the history before payment. Ask how the business should verify the request independently. Do not rely on an attractive permission matrix in a brochure when the operational sequence can be tested directly.
Bring petty cash and reimbursements into the same control framework
Small payments create large reconciliation problems when each site maintains its own informal process. Define who can hold an imprest, which expense evidence is required, who approves replenishment and how the closing cash is verified. Separate cash advanced to a custodian from expenses accepted after review.
Use a simple illustrative reconciliation: opening imprest ₹20,000 plus replenishment ₹10,000, less approved expenses ₹23,000, leaves expected cash ₹7,000 before any other documented movement. The custodian’s count should be compared with that expected balance. A difference needs investigation, not an automatic adjustment to miscellaneous expense.
For reimbursements, identify whether the employee paid personally or received an advance first. Link approved claims to the correct project and period, and check whether the same bill was submitted through another route. A photo of a receipt helps capture the document but does not establish business purpose or approval.
Include these transactions in the pilot. Ask a site user to submit a claim, an approver to return an incomplete claim and accounts to settle the approved version. Then inspect the history and project allocation. The workflow should be practical enough that teams use it for small amounts rather than moving the whole process back to chat.
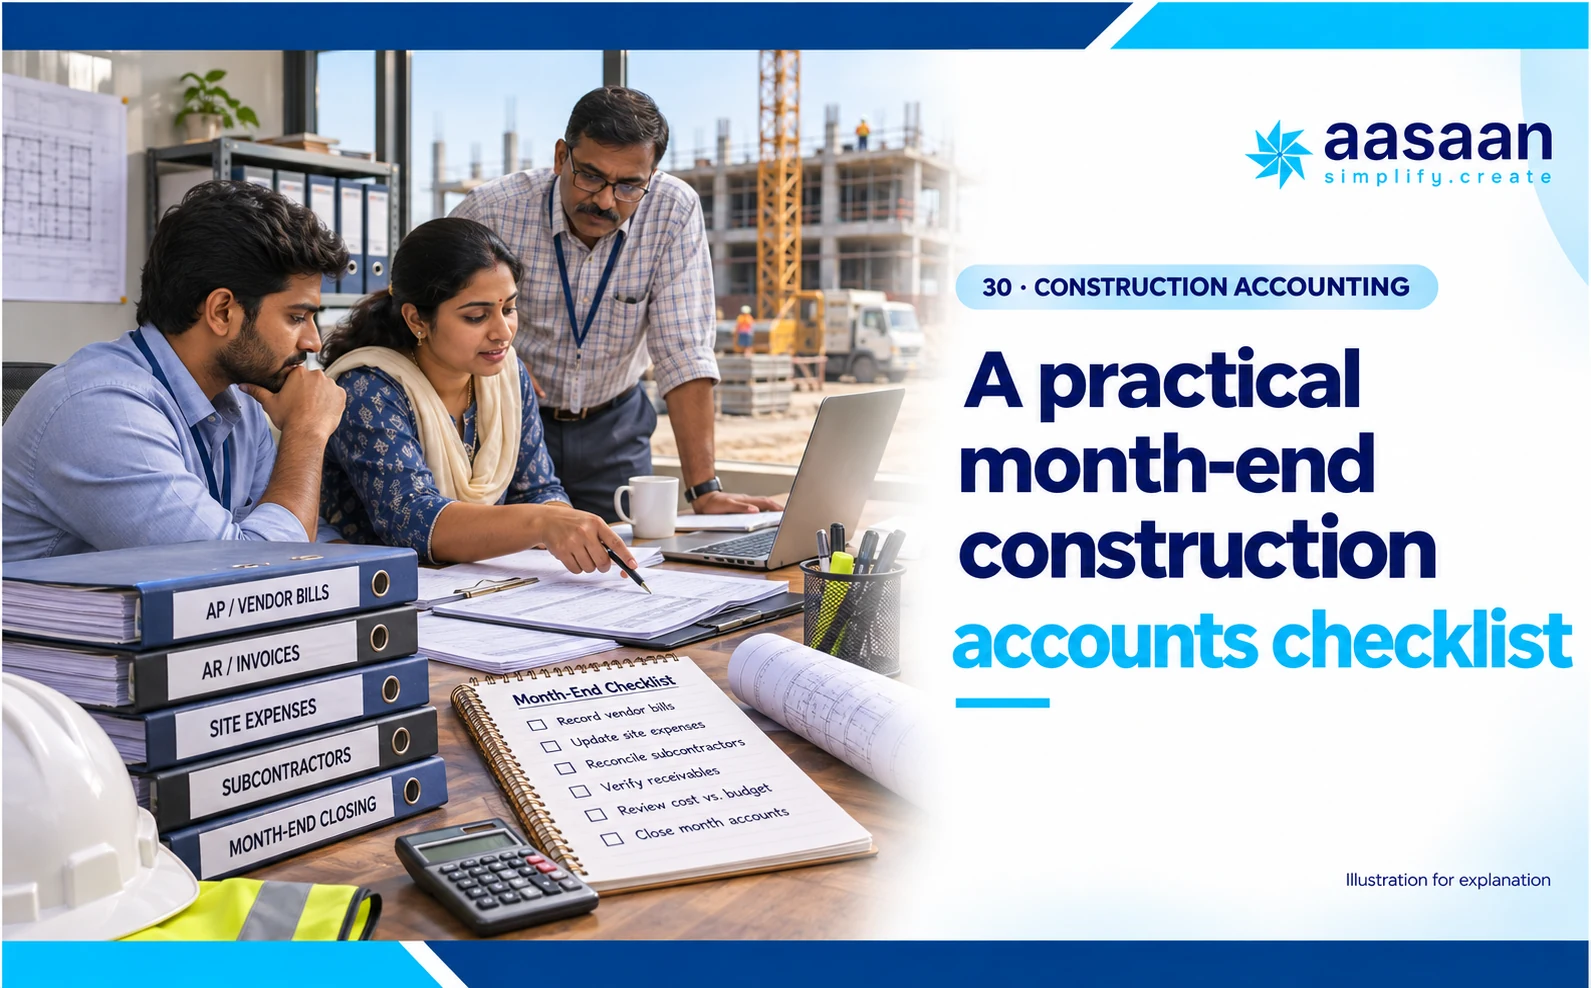
A practical month-end construction accounts checklist
Choose a reporting cut-off and communicate it to the site, purchasing, commercial and accounts teams. Reconcile open receipts, pending invoices, certified subcontractor work and payments in transit. Record items that require accruals or other adjustments for the accountant to review under the applicable policy. Avoid forcing every open item into the same accounting treatment.
Reconcile party balances and obtain statements for significant or disputed accounts. Review advances, retention, credits, unallocated receipts and inter-project allocations. Reconcile bank records to the recorded settlements and investigate differences. A pending transaction should have an owner, the missing evidence and a target resolution date.
Then publish the management view with its basis and remaining exceptions. Show which amounts are confirmed, which are forecast and which are disputed. Preserve the cut-off report so a later correction can be explained. This is how a project owner gets a usable answer without asking the accountant to conceal uncertainty.
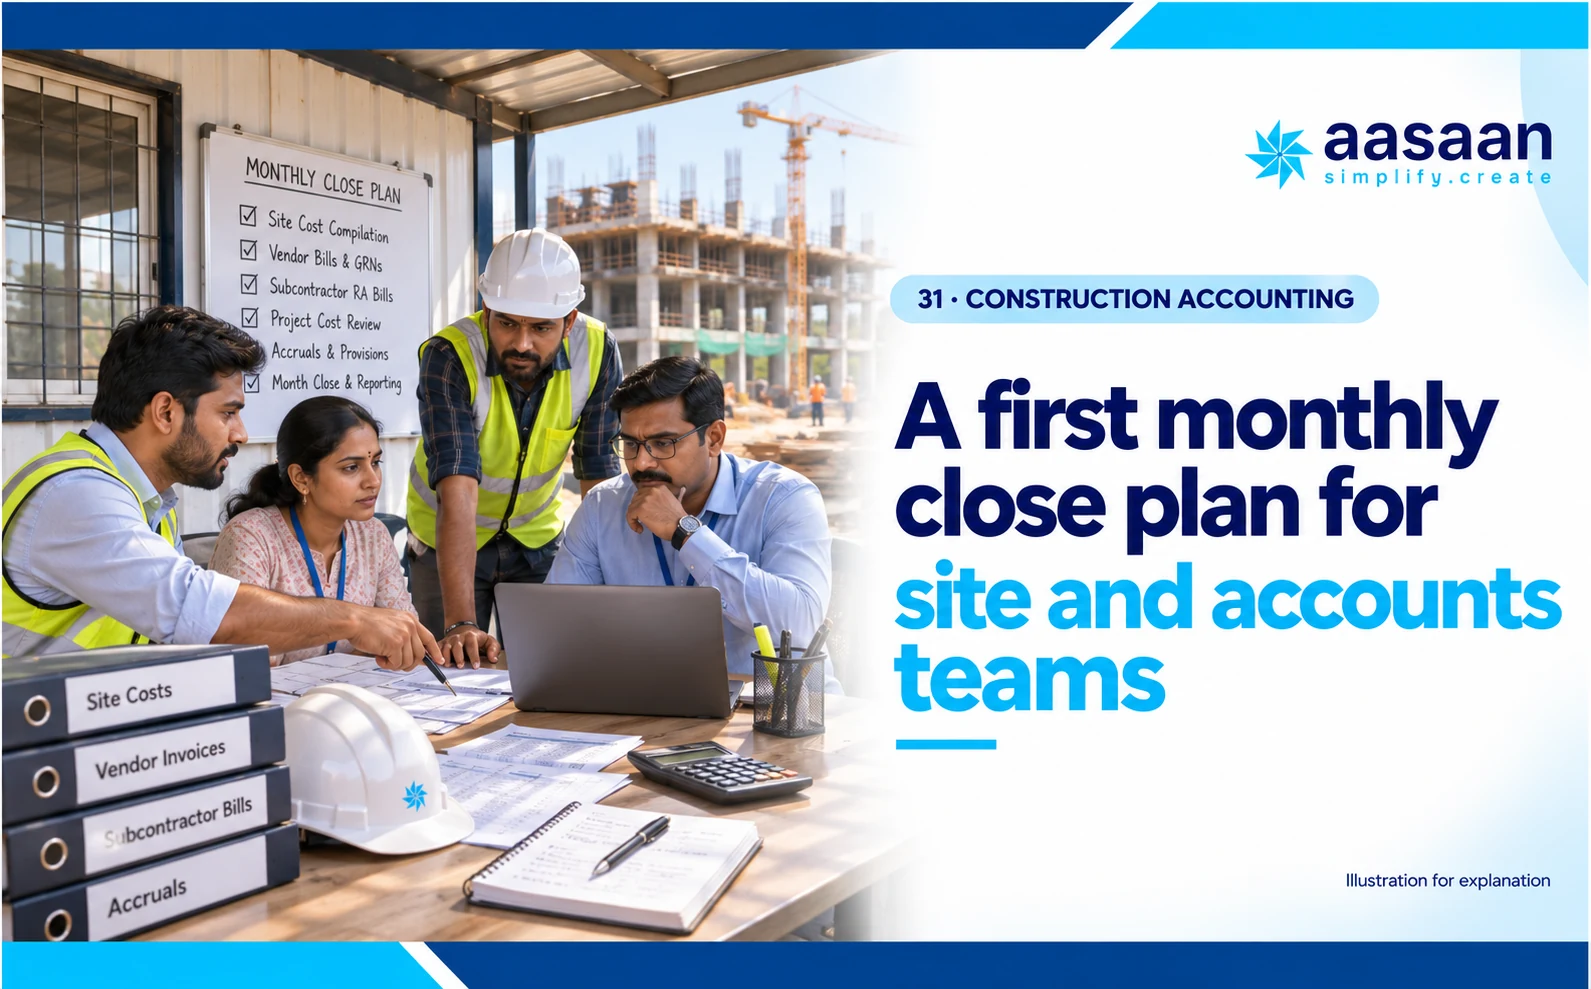
A first monthly close plan for site and accounts teams
Agree the reporting date and the deadline for submitting site evidence. Before that date, the site team reviews open receipts and unsubmitted expense claims; the commercial team reviews measurements and certified work; purchasing reviews delivered-but-unresolved orders. The accountant decides which open items need entries or disclosures under the applicable policy.
Next reconcile major party balances, banks, advances, retention and unallocated collections. Run the GST-related review using current official guidance and your accountant’s process. Resolve or explicitly carry forward exceptions; preserve the reason, owner and expected resolution. When a late document arrives, use the agreed correction procedure rather than silently replacing a previously issued report.
After the close, run a short lessons review. Which missing records caused the most work? Were project codes wrong at capture? Did a transfer fail unnoticed? Did the payment team use a different bill list from accounts? Fix one recurring source problem before the next cycle. Faster close should come from earlier reliable evidence, not from removing necessary checks.
The reports owners, project managers and accountants should see
An owner needs a concise view of upcoming payment demand, collection assumptions, project exposure and decisions waiting for authorisation. A project manager needs package commitments, accepted work, material exceptions and costs needing allocation. The accountant needs reconciled ledgers, source records, tax-review inputs and a controlled close.
Use consistent definitions across those views. A vendor balance can differ from the payment list because some items are not due, are disputed, have unallocated advances or need approval. Let the user drill into that difference. The system should explain why the two numbers differ rather than pretending every report should display the same total.
Ask for freshness information: latest receipt, latest site confirmation, latest accounting transfer and latest reconciliation. ‘Live dashboard’ means little when yesterday’s bill has not been captured. Agree who owns the inputs and what the review cadence is. A reliable daily exception list can be more useful than a complex dashboard whose underlying records nobody checks.
| Reader | Decisions to support | Useful drill-down |
|---|---|---|
| Owner | What needs funding or approval next? | Collection assumptions and payment exceptions |
| Project manager | Which package needs intervention? | Work orders, receipts and certified work |
| Accountant | Do records and balances reconcile? | Source documents, adjustments and transfer history |
| Purchasing lead | Which supplier issue blocks work or payment? | Remaining quantities, delivery and invoice differences |
How Aasaan connects site operations with accounts
Aasaan’s published ERP offering covers supplier billing, client billing, party ledgers and accounting/payment records. It also lists work orders, RA bill history and measured-work RA billing. These capabilities sit alongside procurement, receipts and project operations, giving teams an end-to-end workflow to evaluate rather than an isolated billing screen.
The published hero-features page describes OCR-assisted capture of supplier documents and Tally integration. Treat capture as the start of review: supplier identity, project allocation, amounts and supporting records still need to be checked. Ask how the proposed configuration handles exceptions and who authorises a record before it reaches the accounting system.
The most credible demonstration uses a real, anonymised transaction from your business. Begin at the purchase or work order, show the receipt or measurement, review the bill, trace the payment and reconcile the party balance. Ask the team to repeat the process with a partial receipt, an old advance or a credit note. That is a practical basis for deciding whether Aasaan fits your site-to-accounts requirements.
Product references: Aasaan ERP workflows and Aasaan OCR and integration features.
See how project management connects with the commercial workflow.
How to implement without disrupting the next payment run
Begin with one legal entity and a manageable project or transaction stream. Clean the masters, agree codes and decide the cut-off date. Document opening balances and their source: outstanding invoices, advances, retention, credits, bank positions and unallocated receipts. A single opening vendor total can hide balances that need different treatment.
Reconcile the opening position before entering new transactions. Run a controlled pilot through a complete bill and payment cycle. Use a small parallel comparison to verify outcomes, with one agreed system of record for actual payment release so the team cannot pay from both lists.
Measure exceptions during the pilot: missing project codes, duplicate records, failed transfers, unresolved receipt differences and time taken to reconcile. Fix the cause before adding more sites. Train each role on its own tasks and one common exception. The project is ready to expand when records reconcile and the team can resolve a correction without an implementation consultant reconstructing it.
What should an opening-balance handover contain?
Prepare supporting schedules rather than migrating unexplained totals. For a supplier, separate unpaid invoices, advances, credits and retention where those components are tracked separately under your policies. For customers, preserve the source of outstanding demands, allocations and unallocated receipts. Finance should approve the reconciled position at the agreed cut-off.
Record the source system, extraction date, responsible reviewer and unresolved differences. If you import only a net balance and start processing recoveries separately, you can lose the explanation of what has already been included. Document whether the opening figure is gross or net of each relevant component.
Create a small reconciliation pack for one supplier before loading the entire master. Compare the old-system closing position with the new-system opening position and test the next bill, credit and payment. Ask whether the user can still identify an advance that began before the migration.
Keep one accountable owner for the cut-over decision. The implementation team can import data, but the business must accept the balances and decide how unresolved items are handled. A successful upload message confirms that a file was processed; it does not confirm that the imported financial position is correct.
What affects construction accounting software pricing in India?
Compare the whole proposed setup over a stated period. Ask about user licences, minimum seats, modules, companies, projects, implementation, data migration, training, integrations, hosting, support, renewal terms and exit assistance. Check whether the quoted amount includes applicable taxes. Published starting prices rarely tell you the full implementation cost.
Have each vendor price the same requirements. A quote for accounts-only access is not equivalent to access for storekeepers, site engineers, quantity surveyors and approvers. Equally, do not buy every module simply because the package includes it. Identify the transaction streams that need to work at launch and what can wait.
For Aasaan, request a written scope and current commercial proposal for the required users and integrations. Then ask who supports a failed accounting transfer, what a configuration change costs and how you retrieve usable records at exit. These operational terms can matter more than a small difference in the headline annual price.
What should you test in a construction accounting software demo?
Send a small anonymised evidence pack before the demo: one order, partial receipt, supplier invoice, subcontractor measurement, advance record, payment reference and party statement. Ask the vendor to use these records in a test environment and clearly label any steps that need later configuration.
Run the normal path first, then deliberately introduce an exception. Change the project code before approval, submit the same invoice twice, hold a quantity, apply an authorised credit, make a partial payment and correct a posted entry. Observe what changes downstream and whether the history remains understandable.
Finally, ask different team members to perform their own task. The storekeeper should identify accepted quantities; the quantity surveyor should inspect cumulative certification; the accountant should reconcile; the owner should identify the decision holding up payment. A polished presentation is helpful, but this exercise tells you whether the workflow will survive a busy site.
Construction accounting review tools
Use these illustrations to prepare questions for your accounts review. Enter values in ₹ lakh on a consistent basis. The tools run in your browser; they do not submit your inputs or approve accounting entries. Keep overlapping amounts out of separate fields.
1. Reconcile a remaining settlement amount
Use one defined certified claim or reconciled balance. Enter separately authorised amounts. No tax rate, deduction base or contractual entitlement is inferred.
Worked examples remain available if your browser blocks interactive tools.
2. Plan the cash gap for one period
Use expected cash movements for the same period. A period total does not replace checking the actual dates of receipts and payments. A funding gap is not a profit or loss calculation.
Worked examples remain available if your browser blocks interactive tools.
3. Build your demo agenda
Choose the workflow creating the most avoidable calls today. The questions below help you test the proposed setup; this is a discussion aid, not a vendor score.
Bring an order, partial receipt and invoice. Ask how the quantities are reviewed, who resolves the difference and how the approved bill reaches accounts.
Your construction accounting evaluation checklist
Tick an item only after you have seen the evidence or tested it with your team. Your selections stay on this page for the current visit; they are not a certification of compliance or a saved implementation plan.
0 of 16 checks completed.
A plain-language glossary for your software evaluation
Certified value
The amount of work accepted through the relevant review process. Define whether the displayed figure is for the current period or cumulative.
Committed cost
An obligation from an order or contract. Establish whether a report includes already incurred costs so you do not add the same amount twice.
Outstanding payable
The reconciled unpaid balance on the chosen reporting basis. Part of it may not yet be due or approved for the next payment run.
Retention
A contractually withheld amount with agreed release conditions. Keep its balance and release authority separate from routine invoice approval.
Advance
Money provided before the related settlement or performance. Maintain a schedule showing how it is adjusted or recovered under the agreed terms.
Credit note
A document adjusting a supplier claim or transaction. Follow it through recording, allocation and settlement rather than treating receipt of the document as closure.
GRN
A goods receipt note records receipt information. The record should identify the relevant order, delivered quantity and acceptance status used by your workflow.
Reconciliation
An explanation of how two records or balances relate, including timing differences, missing entries, adjustments and the actions required to resolve discrepancies.
Frequently asked questions
What is the best construction accounting software in India?
The best fit depends on where your current process breaks. For a books-and-compliance requirement, evaluate accounting depth with your accountant. For missing site evidence, uncertified bills and disconnected approvals, evaluate construction ERP and its accounting handoff. Aasaan is worth shortlisting for connected site-to-accounts workflows; use your documents to test supplier billing, work orders, RA bills, payments and integration rather than selecting solely from a feature list.
Can I continue using Tally with construction software?
You may be able to keep Tally as the accounting system while a construction platform manages upstream site records and commercial workflows. Agree which system owns masters, approvals, postings and corrections. Aasaan publicly lists Tally integration, but the proposed versions, transaction coverage, configuration and charges should be demonstrated and included in your scope. Test a correction and a failed transfer as well as a successful bill.
Is construction cost tracking the same as accounting?
No. A site cost tracker can monitor spending, budgets or forecast costs without maintaining the statutory books. Accounting also needs the appropriate postings, reconciliations, reporting basis and controls. Connect the two through consistent project codes and agreed rules. The accounts team should explain how operational amounts become accounting records and how the totals reconcile at cut-off.
How do I know the actual amount payable to a subcontractor?
Start with a clearly defined certified claim or reconciled cumulative balance. Review applicable tax amounts and the contractually authorised retention, advance recovery and other adjustments. Reconcile earlier certifications and payments so nothing is deducted twice. Keep amounts not yet due, disputed or awaiting approval separate from approved settlement. The calculator in this guide illustrates arithmetic only; it does not certify a bill or decide its tax treatment.
Does a positive site cash balance mean the project is profitable?
No. Cash can include customer advances or funding, while important supplier or subcontractor obligations remain unpaid. Profit also depends on the adopted revenue and cost-recognition policies. Review bank cash, receivables, payables, advances, retention and forecast remaining work separately. Use the cash planner for timing and funding decisions, then obtain the appropriate accounting report for profitability.
Can construction accounting software manage multiple projects and companies?
Many products offer project or company structures, but the details vary. Test the legal entity on the source transaction, project allocation, permissions and the treatment of shared vendors. Consolidation should not blur the books of different companies. Ask for the exact cross-company and project-reporting requirements in the implementation scope, including how errors are corrected and how each entity’s balances are reconciled.
Should the software automatically apply GST and TDS?
It should support the settings, approvals and review workflow your finance team requires. Automation does not remove the need to establish the applicable treatment. Ask who maintains settings, how effective dates and exceptions are handled, and how corrections are reviewed. Avoid evaluating the product with a single tax rate: take representative transactions from your own contracts and have the accountant validate the outcome.
Can OCR eliminate invoice verification?
OCR can reduce the effort of capturing document fields, but a captured amount can still be allocated to the wrong project or refer to a quantity the site has not accepted. Review the supplier, document reference, line items, totals and supporting order or receipt. Ask how confidence issues, duplicates and amendments are handled. Aasaan lists OCR-assisted document capture; test the review path rather than assuming extraction equals approval.
How much does construction accounting software cost?
The cost depends on the proposed users, entities, modules, integrations and implementation effort. Request a quote for the same launch scope from every vendor and include migration, training, support and renewal terms. Compare the total cost over an agreed period. A current written proposal is a better purchasing reference than a generic price copied from an old comparison article.
How should we start implementing construction accounting software?
Start with a defined transaction stream, cleaned masters and reconciled opening balances. Pilot one complete bill-to-payment cycle with a named owner in each team. Agree the system of record for actual payments, test corrections and reconcile the output before expanding. Keep a short list of unresolved exceptions with owners so rollout progress is measured by reliable outcomes rather than login counts.
References and further reading
The following references support the product descriptions and accounting-review context. The examples, tables and checklists in this guide are original illustrations. External source links are references; they do not imply endorsement of Aasaan.